Credit Repair Chicago Residents Can Actually Verify
Searching for credit repair in Chicago turns up dozens of companies promising fast scores and guaranteed deletions. Most of those promises are illegal to make. Legendary Ways Credit Solution takes the opposite approach: we only dispute what federal law says is disputable, we put every step in writing, and we never charge a dollar before work is performed, because the Credit Repair Organizations Act forbids it.
The scale of the problem is real. The Federal Trade Commission’s landmark accuracy study found that one in five U.S. consumers has an error on at least one credit report, and the CFPB has logged millions of credit-reporting complaints. In a metro the size of Chicago, the second most populous county in America, that is hundreds of thousands of people paying higher rates on mortgages, auto loans, and rentals because of entries that should not be on their reports. Credit repair Chicago families can trust starts with finding those entries and challenging them correctly.
How Our Credit Repair Chicago Process Works
Free consultation
A phone or video call where we hear your situation and tell you honestly whether professional credit repair is worth paying for in your case. If doing it yourself is the better answer, we say so and point you to our free guides.
Three-bureau analysis
We review your Equifax, Experian, and TransUnion reports with you, line by line, and deliver a written breakdown: what is accurate, what is disputable, and which score factors matter most in your file.
Disputes filed & tracked
Every inaccurate, incomplete, outdated, or unverifiable item is disputed with the bureaus under the Fair Credit Reporting Act. Bureaus generally have 30 days to investigate and answer in writing.
Escalation when needed
When a bureau verifies an item that is provably wrong, we escalate: furnisher disputes with documentation, method-of-verification requests, CFPB complaints that force a response, and Illinois Attorney General complaints for in-state leverage.
Rebuild & report
Alongside disputes you get a rebuilding plan, utilization timing, payment automation, account-age protection, and a written progress report after every cycle showing exactly what happened and what comes next.
What We Look For on a Chicago Credit File
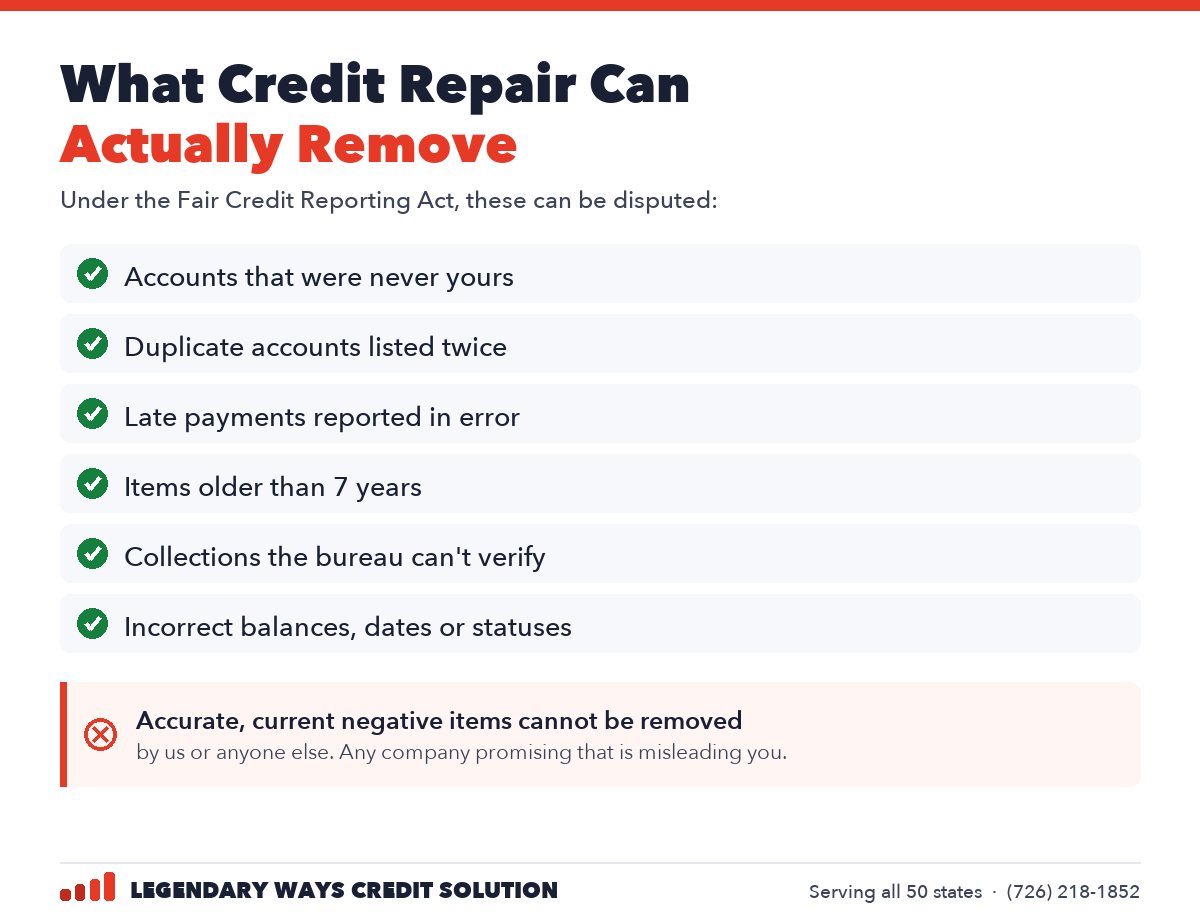
Medical collections that break current rules
RULE VIOLATION
The bureaus no longer report paid medical collections or medical collections under $500, and wait a year before unpaid bills appear. In a county with Chicago’s hospital concentration, entries violating these rules are routine and fully disputable. See our Illinois medical collections guide.
Obsolete and re-aged items
TIME LIMIT
Most negatives must come off seven years from first delinquency; Chapter 7 after ten. Collectors sometimes illegally re-age debts to keep them reporting, one of the strongest dispute grounds in the FCRA.
Mixed files and identity errors
IDENTITY
Common names and shared addresses put other people’s accounts on your report. In a metro this size, mixed-file errors are routine and disputable with identity documentation.
Wrong balances, statuses and dates
FACTUAL
Paid collections showing unpaid. Bankruptcy-discharged accounts still reporting balances. Lates during documented forbearance. Each is a factual inaccuracy the bureaus must investigate.
Duplicate collection entries
DUPLICATE
When a debt is sold between collectors, both sometimes report at once, doubling the damage of one debt. Only the current owner may report.
What we will never dispute
Accurate, timely, verifiable information. No company can legally remove it, and anyone promising to is describing fraud. For accurate items, the answer is the rebuilding plan.
Who We Typically Help in Chicago
Renters facing screening
Chicago is a majority-renter city and most management companies screen credit. An old collection or mixed-file error can sink an application your income would otherwise carry.
First-time homebuyers
IHDA programs and conventional lenders price by score band. Correcting report errors before underwriting protects both the approval and the rate on every month of a 30-year loan.
Workers rebuilding after layoffs
Hospitality, transportation, and service employment here saw deep pandemic disruption. Delinquencies from documented layoff periods are where goodwill letters and dispute work both apply.
Small business owners
Lenders underwrite your personal credit alongside the business. The Federal Reserve’s small business survey shows approval rates roughly double for low-credit-risk applicants.
After bankruptcy, divorce, or repossession
Equal parts correcting what is misreported and rebuilding positive history in the right order, our rebuilding guide covers the sequence.
Not sure where you fit?
The free consultation is still the right start. We will tell you honestly whether professional help is worth paying for in your case.
How Remote Service Works for Chicago Clients
Credit repair is document work, and every part of it happens securely online or by phone: consultations by phone or video at times that fit your schedule, reports and documents handled through secure channels, and a direct line to the people actually working your file. We do not have a Chicago office and will never pretend to, the bureaus are in other states no matter where your provider sits, so what you are paying for is the quality of analysis and the persistence of escalation, not a lobby.
Chicago clients get the same process, the same written reporting, and the same CROA and Illinois CSO Act protections as anyone sitting across a desk, without the commute on the Kennedy.
Pricing, Transparency, and What Illinois Law Requires
Federal law shapes how any honest company charges. Under CROA, payment cannot be collected before services are performed, so legitimate companies, ours included, bill after work is completed each cycle, never as an upfront lump sum. Before anything begins you receive a written contract stating the services, schedule, total cost, and your three-day right to cancel without penalty.
Illinois adds its own layer: the Illinois Credit Services Organizations Act requires companies serving Illinois residents to register with the Secretary of State, maintain a surety bond you can claim against, and provide state disclosures before signing. Exact pricing depends on your file’s complexity and is established in the free consultation, in writing, before you commit to anything.
The test that protects you: if any company, including ours, asks for payment before work is performed, refuses a written contract, or dodges the Illinois registration question, that is your answer about them. Our five-question vetting guide gives you the full checklist.
Start Your Credit Repair Chicago Review Today
Tell us a little about your situation and we will reach out to schedule your free consultation. You leave the first conversation knowing exactly what is disputable in your file and what the realistic path looks like, whether or not you hire us.
Request Your Free Consultation
No fees before work is performed. No obligation.
Prefer to Do It Yourself? Start Here
Disputing credit report errors is free and legal for every consumer, and for a file with one or two obvious errors it is genuinely the better option. Pull all three reports free at AnnualCreditReport.com, available weekly at no cost, then use our guides:
Fix your score: the plan
Utilization timing, payment automation, rebuilding in order, read the plan.
Where professional help earns its fee: many negatives across all three bureaus, mixed files, identity theft, re-aged debts, and furnishers that keep verifying provably wrong items. Those files need documentation strategy across multiple cycles, exactly the work we do.
Free Chicago Credit Resources
Every guide below is sourced, compliant, and written for Illinois consumers, use them with or without us.
Credit Repair Chicago: Your Questions Answered
Is credit repair legal in Chicago?
Yes. Credit repair is legal throughout Illinois when performed under the federal Credit Repair Organizations Act and the Illinois Credit Services Organizations Act, which require registration, bonding, written contracts, and no advance fees.
Do you have an office in Chicago?
No, we serve Chicago clients remotely, as we do clients in all 50 states. Consultations happen by phone or video and documents are handled securely online. Credit repair is analysis and correspondence, not an office visit.
Can you remove accurate negative items?
No, and no company legally can. We dispute items that are inaccurate, incomplete, outdated, or unverifiable. For accurate items, we build a plan around utilization, payment history, and rebuilding tools, the factors that actually move scores over time.
How long does credit repair take?
Dispute cycles run roughly 30-45 days each. Simple files may need one or two cycles; complex files with items across all three bureaus typically take several months. You get a realistic estimate after the first review, in writing.
Will disputing items hurt my credit score?
No. Filing a dispute is a consumer right under the FCRA and is not itself scored. What hurts is closing old accounts or applying for new credit mid-process, which is why our plan covers what not to touch while disputes run.
What if a bureau verifies an item that is wrong?
Verification is not the end. We dispute directly with the furnisher, add documentation, file CFPB complaints that require a company response, and use Illinois Attorney General complaints for in-state leverage. Persistent, documented escalation is where much of our value sits.
How do I get started?
Book the free consultation online or call (726) 218-1852. Have your reports ready if you can, AnnualCreditReport.com provides them free weekly, or we will walk you through pulling them on the call. You leave knowing what is disputable in your file, whether or not you hire us.
Is DIY credit repair a real option?
Absolutely, disputing is free for every consumer, and for simple files it is the better path. Our guides cover the whole process; professional help earns its fee on complex, multi-bureau files.
Start With the Free Credit Review
One honest conversation about your reports. You leave knowing what is disputable and what the realistic path looks like, whether or not you hire us.
(726) 218-1852 · Info@legendarywayscreditsolution.com · Serving Chicago and all 50 states remotely
Legal notice: Legendary Ways Credit Solution serves Illinois clients remotely and does not guarantee any specific score outcome. No company can legally remove accurate, timely, verifiable information from a credit report. We dispute items that are inaccurate, incomplete, outdated, or unverifiable under the Fair Credit Reporting Act. Results vary by individual credit profile.